Investing in Argentina's Energy Transformation
Real Assets · Private Markets · Vaca Muerta
September, 2026
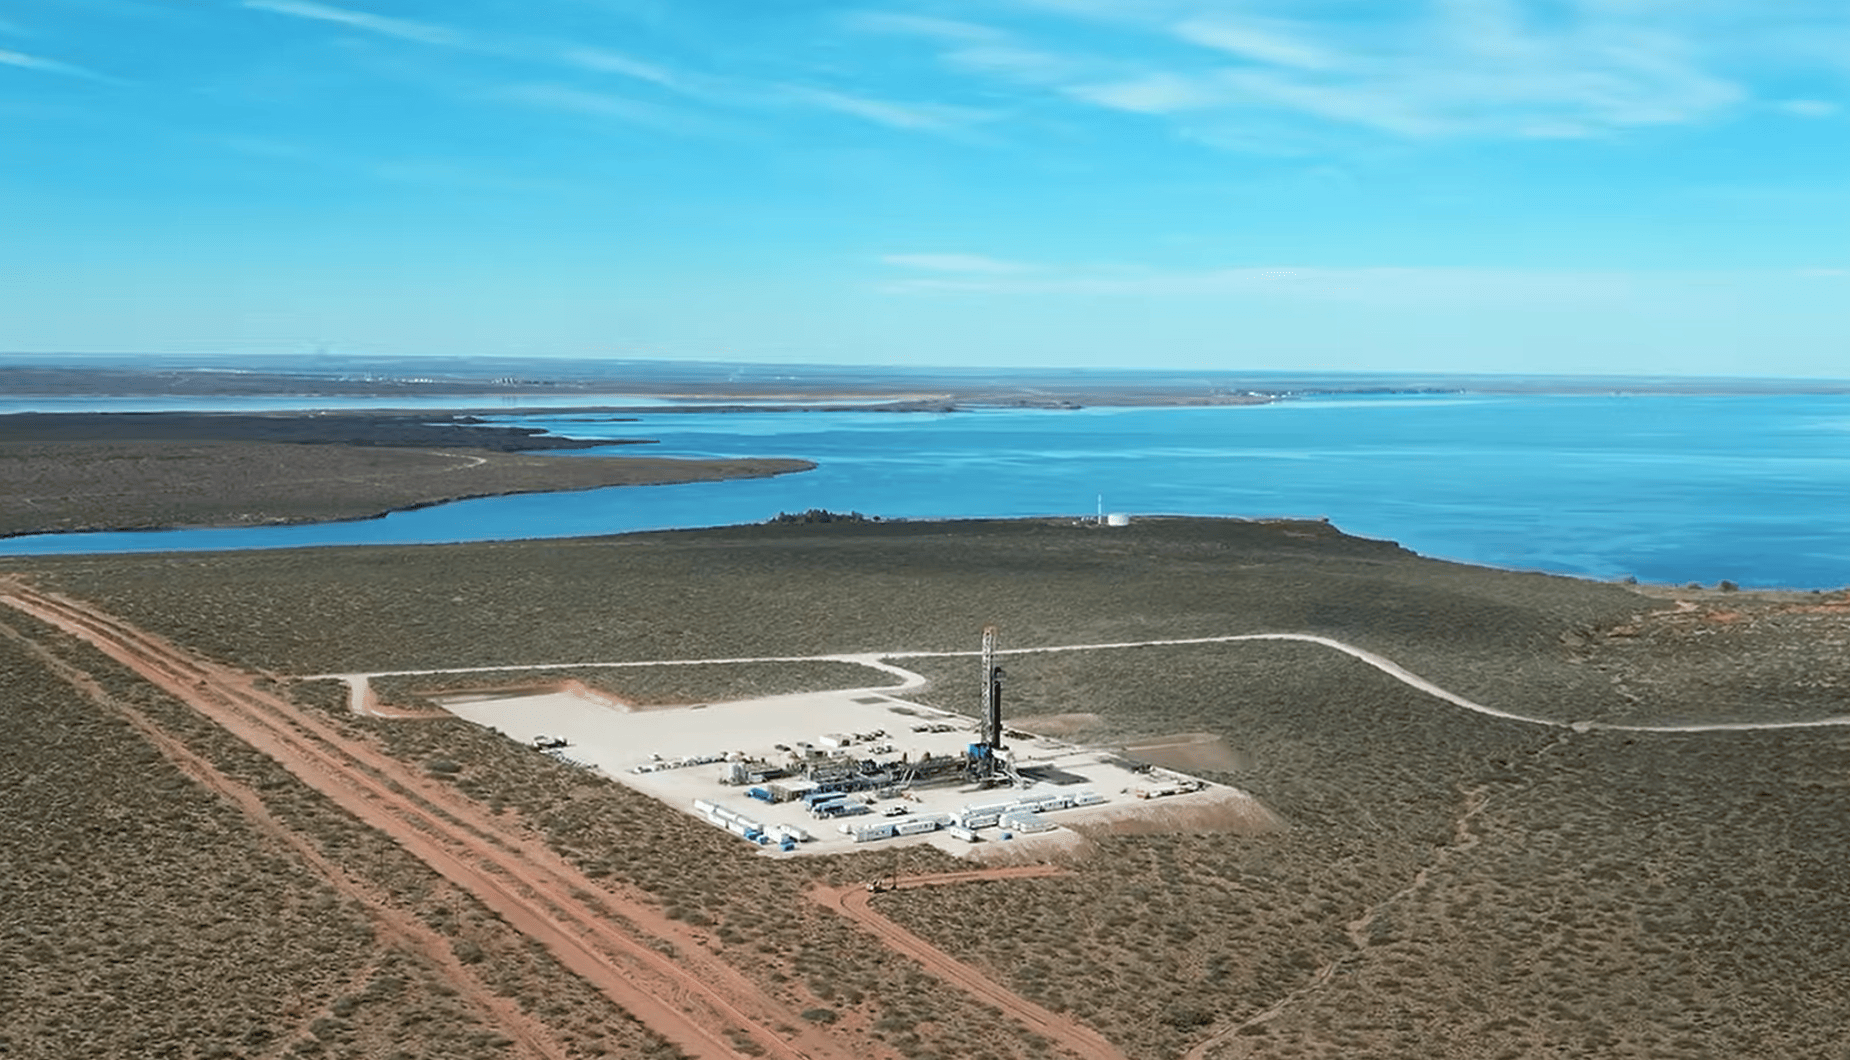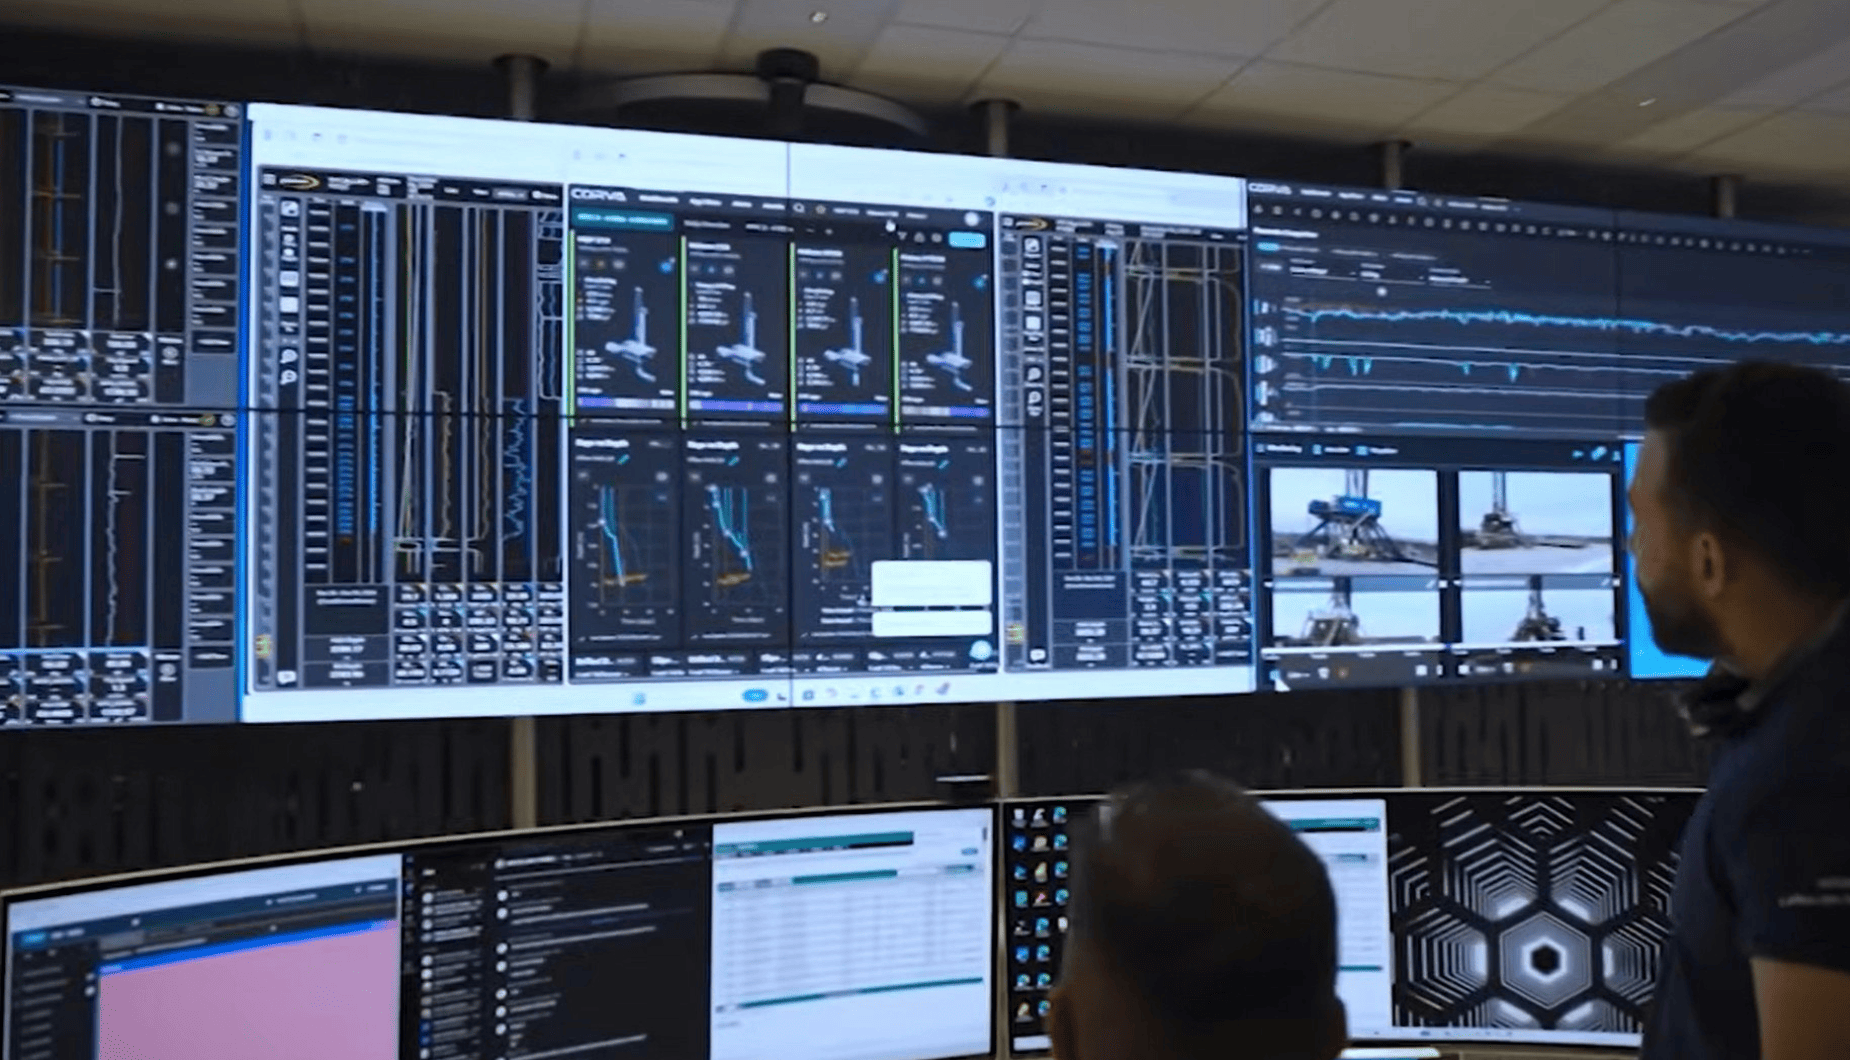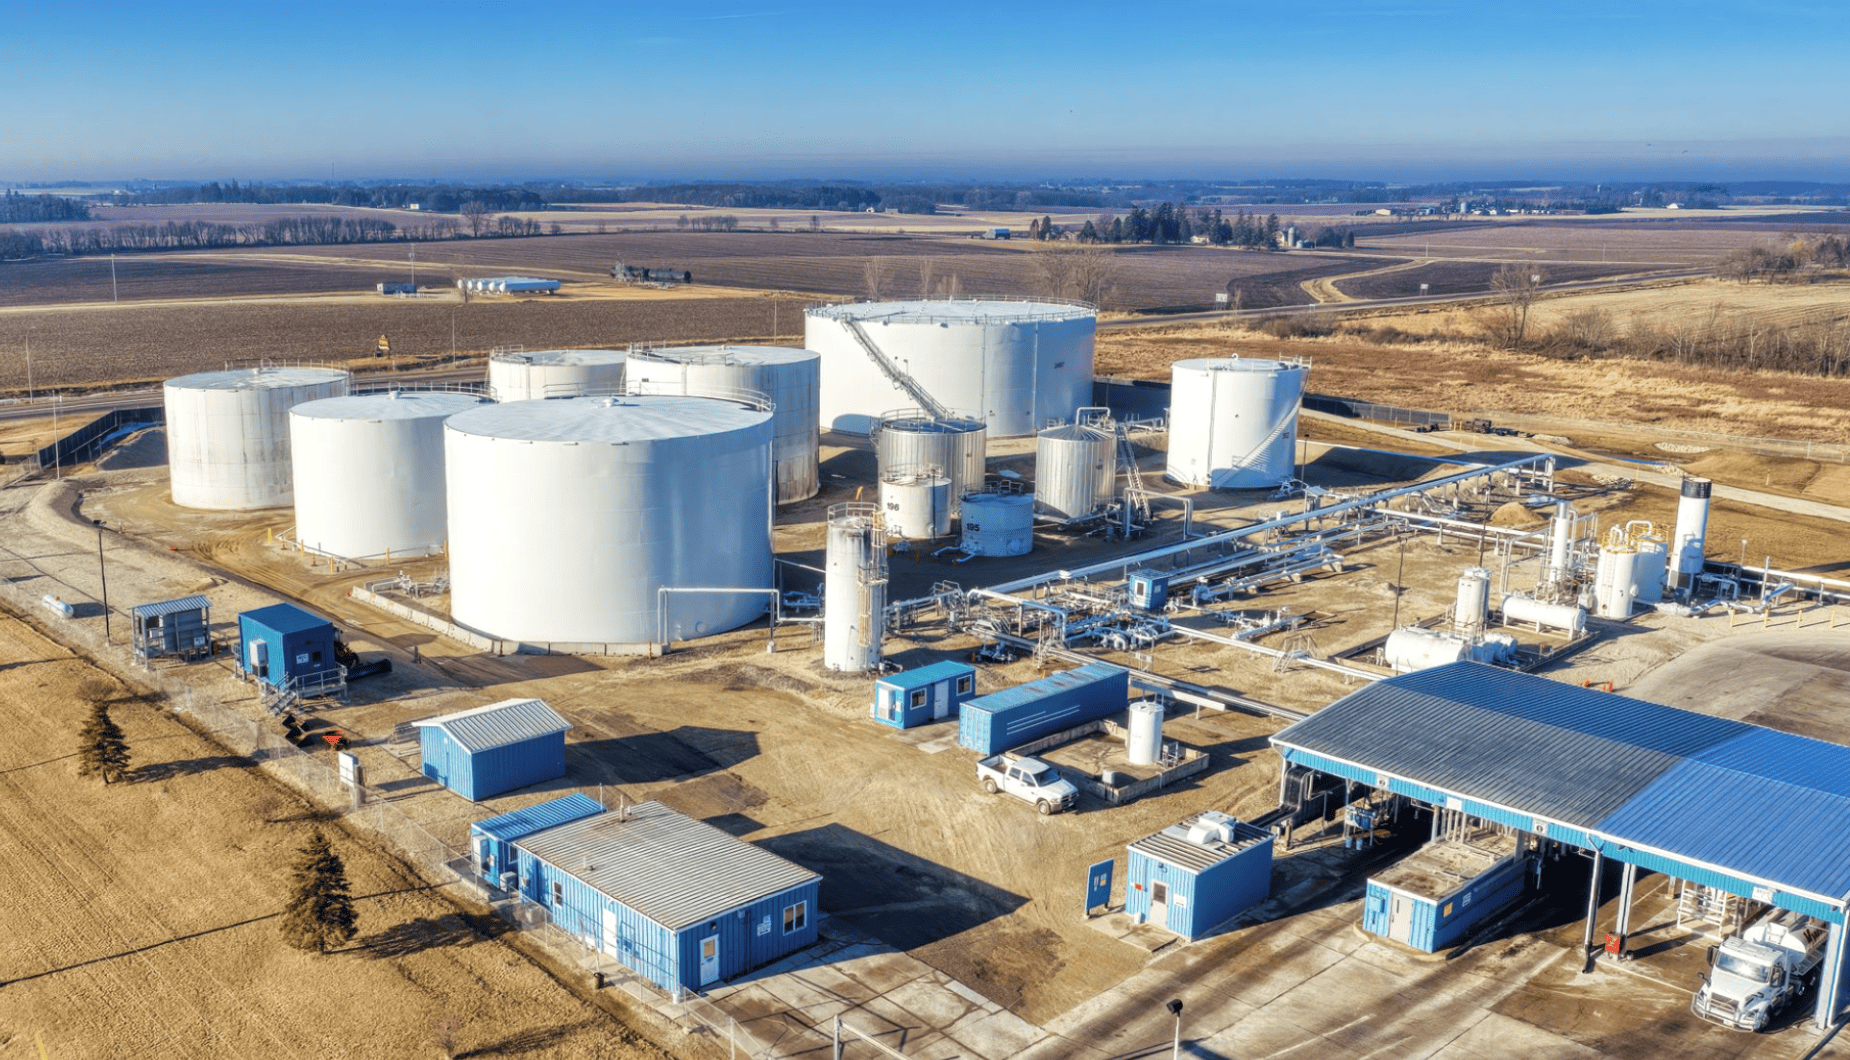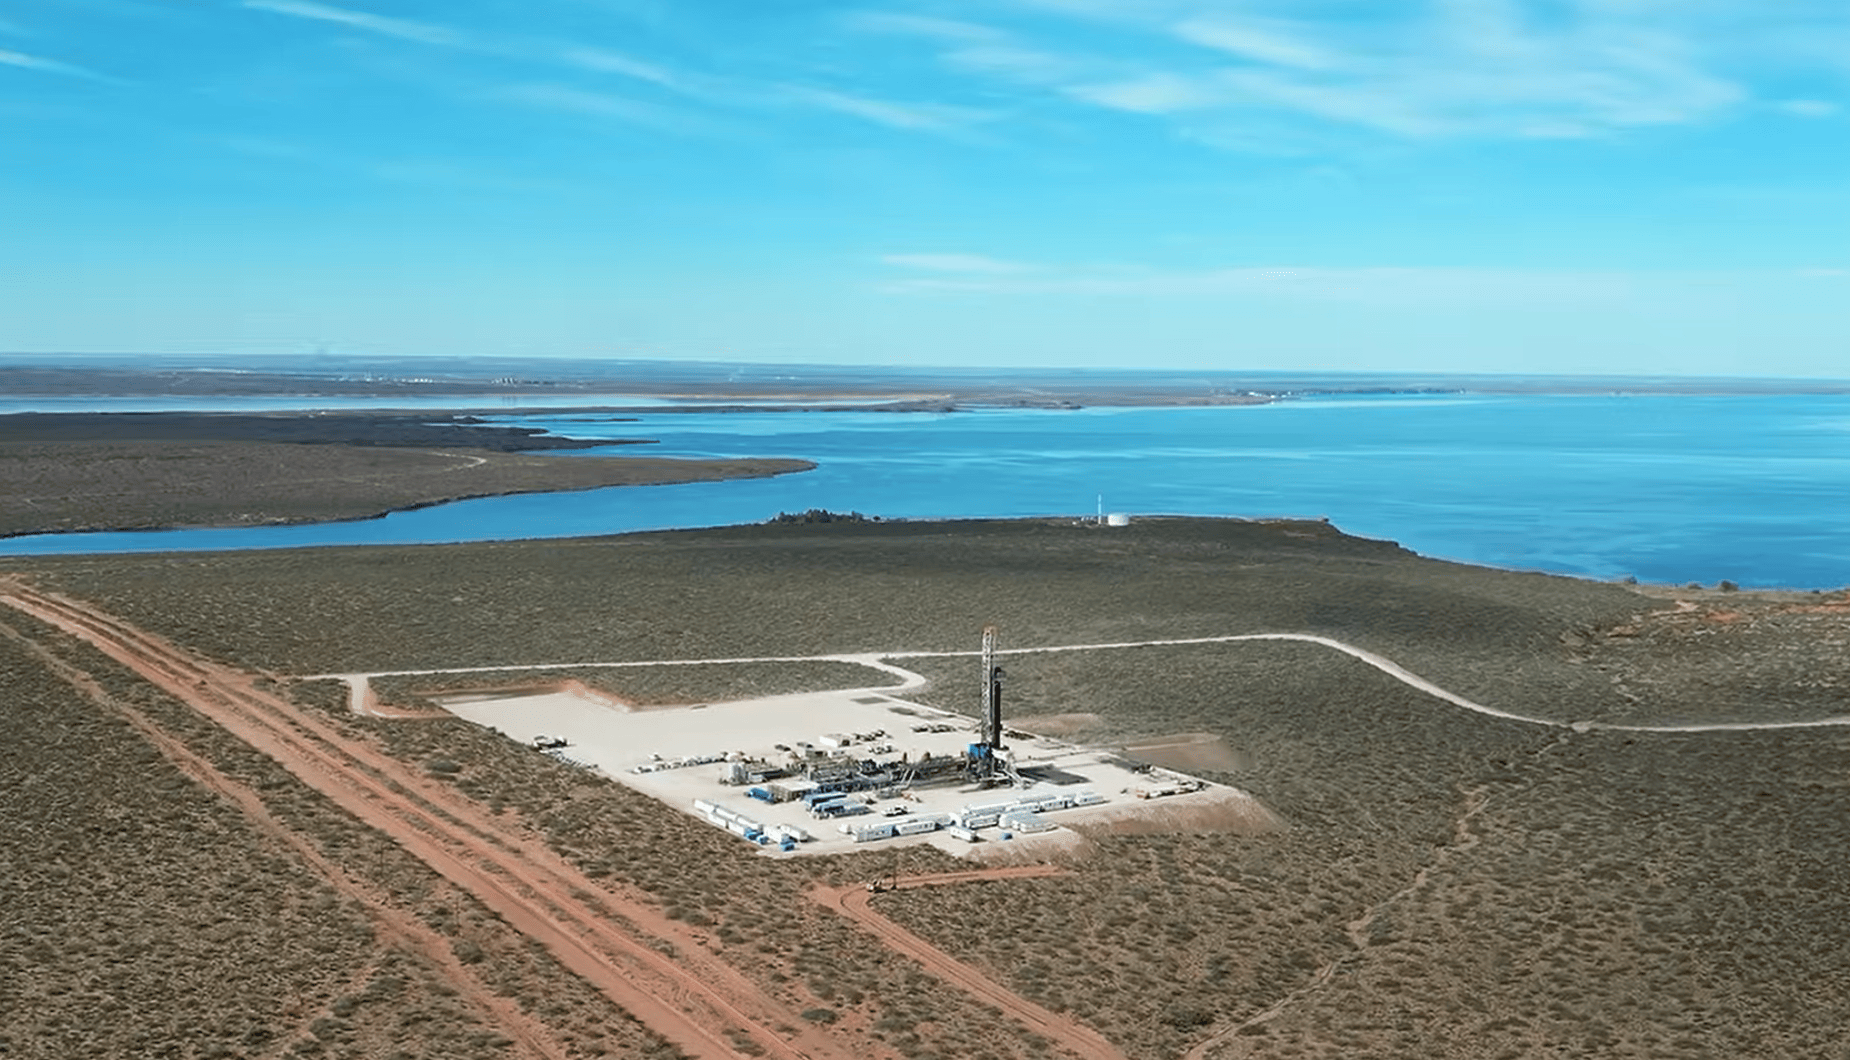
G. Berthout & Cie is a private capital advisory group* focused on opportunities arising from Argentina's energy transformation. We combine international investment expertise with deep local knowledge and technical judgement to identify, underwrite and structure deals across Vaca Muerta's real-asset landscape, with a primary focus on upstream development and selective exposure to opportunistic energy infrastructure. We work with institutional investors seeking exposure to real assets through private equity and private credit.
* To view the Notice & Disclaimer again, refresh this page.
01. MACRO
Argentina: The Stabilisation
Key economic improvements Dec 2023–Aug 2026:
INFLATION
210% →
33%
CPI YoY
FISCAL BALANCE
-2.8% →
+0.3%
% of GDP; 2024 first
surplus since 2008.
COUNTRY RISK
>2,000 →
~500
Sovereign Spread
(basis points)
EQUITIES
+110%
in USD
REAL GDP
+4.4% / +3.5% /
+4%
2025 / 2026E /
2027E1
1 Source: IMF, World Economic Outlook Update, July 2026.
│ Markets have responded positively to the improving macroeconomic outlook.
Investment Environment
For energy investors, the significance is practical: Argentina's investment environment is becoming more supportive of long-duration private capital. A more market-oriented economic policy, reduced regulatory intervention and greater openness to international trade and investment are improving the conditions for private capital formation. At the same time, stronger engagement with international markets and strategic partners is supporting greater confidence in Argentina as a destination for long-term investment.
RIGI2
Argentina's 2024 investment incentive regime provides qualifying large-scale investments with a more predictable tax, customs and foreign-exchange framework, materially improving project economics and bankability. The regime also reduces several of the regulatory, tax and capital-mobility constraints that have historically limited investment in the country.
Projects spanning energy, mining and other strategic sectors:
US$ 47bn+
Projects Approved by Government
US$ 151bn+
Projects Under Review
2 Régimen de Incentivo para Grandes Inversiones (RIGI). Law No. 27.742, enacted 27 Jun 2024.
02. THE BASIN
Why Vaca Muerta?
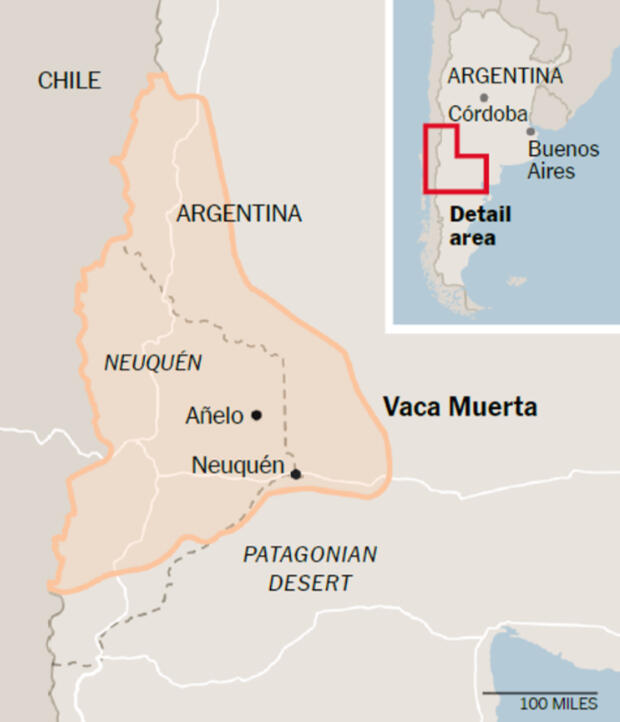
Vaca Muerta is one of the world's largest unconventional hydrocarbon formations, located within Argentina's Neuquén Basin and spanning primarily the provinces of Neuquén, Mendoza and Río Negro.Identified almost a century ago, modern development only began with the first horizontal drilling and hydraulic-fracturing pilot wells in 2010, followed by commercial-scale development from 2013.A very thick, organic-rich marine shale of Late Jurassic to Early Cretaceous age, with reservoir thickness ranging from 160–400 metres and exceeding 700 metres in the basin centre, placing it closer in scale to the Permian’s Wolfcamp than to Eagle Ford or Bakken basins in the US.Development relies on deep vertical drilling (3 km) followed by lateral drilling (3 km+) and multi-stage (50) fracking. These characteristics support its globally significant resources, growing production, competitive economics and decades of development runway.
2nd
Largest shale gas
resource globally
4th
Largest shale oil
resource globally
16bn+ bbl
Technically
recoverable oil
(Source: US EIA 2013)
300+ Tcf
Technically
recoverable gas
(Source: US EIA 2013)
30,000 km²
Formation area,
~Belgium-sized
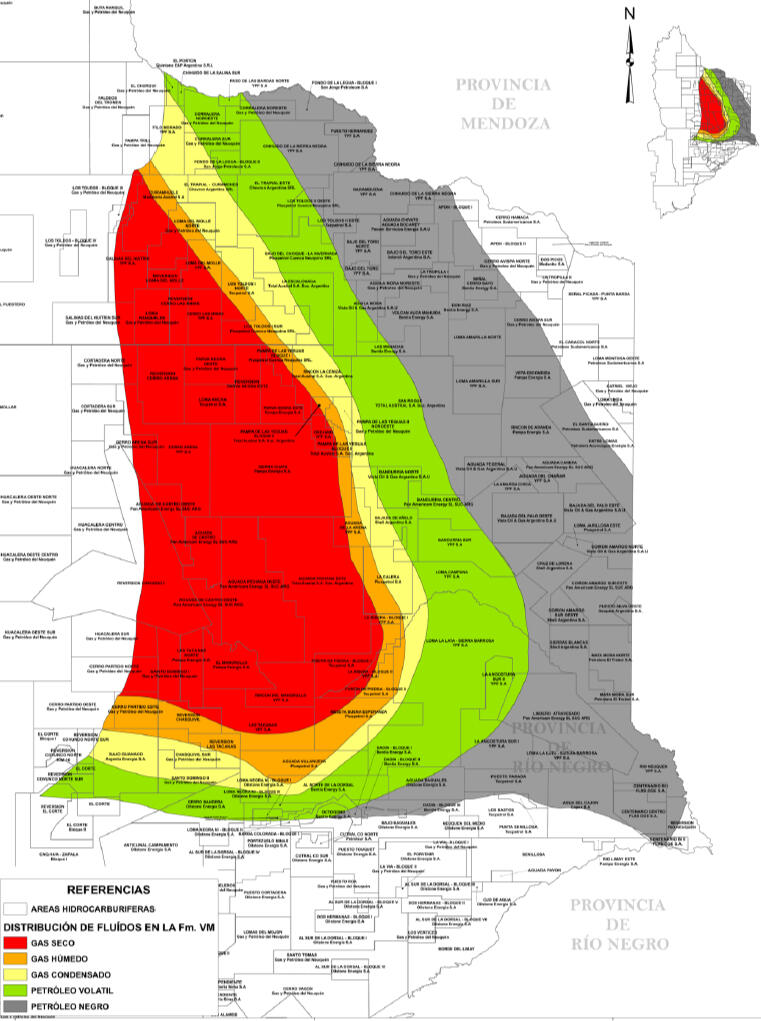
Hydrocarbons
CRUDE OIL
Grade: Medanito
Lighter and sweeter than WTI, with an API gravity of 40.8–42.5° and low sulfur content (0.15–0.21%). Quality is highly comparable to WTI, and it trades between WTI Cushing and ICE Brent on a FOB basis.
NATURAL GAS
Dry / Wet
Mostly Methane C1
NATGAS LIQUIDS (NGLs)
LPG / Condensates
Ethane C2
Propane C3
Butane C4
Condensate /
Pentanes C5+
UPSTREAM: FLUIDS MAP
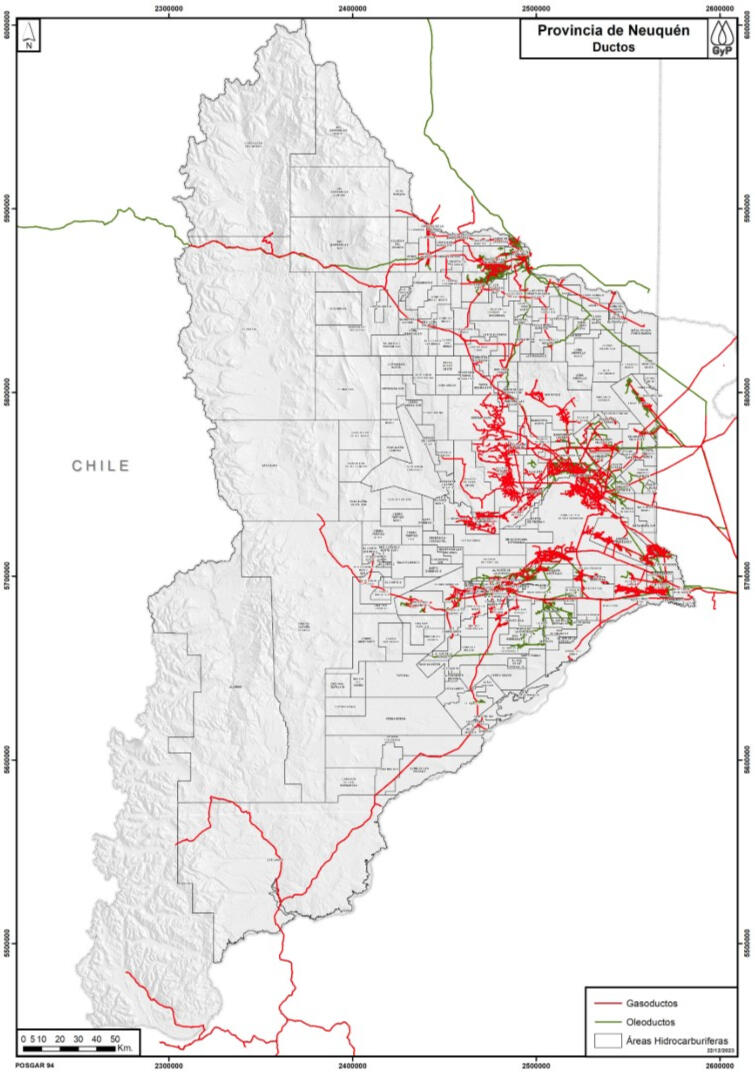
MIDSTREAM DUCTS (NEUQUÉN)
640 kbpd
Shale oil output,
Jul 2026
(Thousand barrels/day)
3.4 Bcf/d
Shale gas output,
Jul 2026
(Billion cubic feet/day)
US$ 35–50/bbl
Brent breakeven range
for new wells vs $62–70/bbl WTI in US shale3
15.8 vs 18 vs 23
Carbon Intensity Index4
Vaca Muerta vs OGCI members vs Global Avg (kg CO2e / boe)
~4%
Estimated resource
produced to date
3 Source: Federal Reserve of Dallas. Energy Survey 2026.
4 Source: McKinsey & Co., "Vaca Muerta: An opportunity to respond to the global energy crisis", Oct 2022.
│ “Vaca Muerta’s well productivity already rivals the best of the US Permian Basin on a normalised basis”;
“outperforming plays such as the Permian, Bakken, and Eagle Ford on well productivity measures.”5
5 Rystad Energy (2026)
│ Reported carbon intensity is materially below both the OGCI6 member average and the global oil & gas average.
6 Oil and Gas Climate Initiative. The world's 12 leading energy companies work individually and collectively to accelerate action to achieve net-zero emissions by 2050.
MOMENTUM
Production is scaling as upstream drilling activity, midstream evacuation capacity, and export infrastructure expand. Extensive exploration has substantially de-risked the geological uncertainty across much of the basin, shifting the focus from resource delineation towards development and industrial-scale production.
~70%
of Argentina's total
crude oil production
+33%
shale oil output YoY,
as of Jul '26
+10%
shale gas output YoY, as of Jul '26
~2,800 / 500
total active producing
wells (oil & gas) / exp new wells in 20267
20
13 operating + 7 non-operating companies
7 Compared with ~200,000 producing wells in the Permian Basin and 6,000 new wells in 2026. Source: CommoVision (Jun 2026)
DEVELOPMENT AT SCALE
The formation's development is entering a phase of sustained, large-scale capital deployment. For Argentina, Vaca Muerta is strategically important beyond energy security: rising hydrocarbon production is turning the country into a net energy exporter, generating much-needed foreign currency, strengthening the external balance and supporting fiscal stability.
US$ 60-95bn
estimated cumulative investment through 20308
US$ 6bn
energy trade surplus
H1'26
+60%
crude oil exports YoY,
as of Jul '26
US$ 50bn
expected energy exports
in 2031. (Source: YPF)
8 McKinsey & Co: "Vaca Muerta’s next leap: Integrating the energy value chain at scale", 5 May 2026.
03. GLOBAL ATTENTION
Entering the Mainstream
│ The basin is increasingly recognised as a significant global energy opportunity by investors, energy companies and financial institutions.
04. TIMING
Why now?
Infrastructure Is Catching Up
As production scales, new pipelines, export capacity (FLNGs9) and associated infrastructure are expanding to unlock the basin's full potential.
9 "Floating Liquefied Natural Gas" vessels: Hilli Episeyo (exp late '27), and MK II (exp late '28).
RIGI2 Window
Applications remain open through July 2027, providing a defined window for new large-scale investment.
Geographic Security
Argentina offers a growing energy supply from the South Atlantic, with exports that are not dependent on passage through major maritime chokepoints such as Hormuz, Suez, Bab el-Mandeb, Malacca, Panama or Gibraltar.
05. INVESTMENT OPPORTUNITY
Private Markets: Where We Focus
Argentina's energy and infrastructure opportunity is predominantly private.
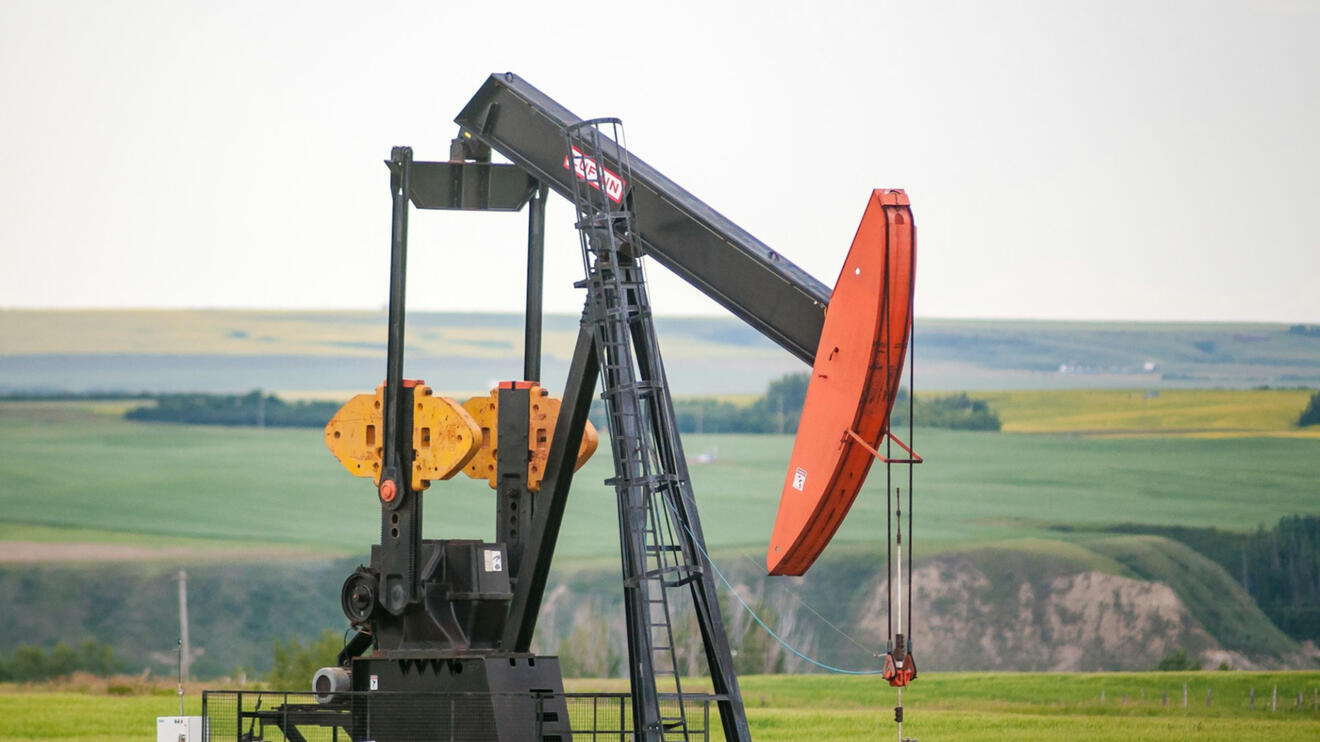
UPSTREAM
Oil & Gas Production
Non-operated working interests and partnerships at the asset level. Production provides direct commodity exposure, with capital returned through operating cash flows rather than a conventional private equity exit.
Higher Return / Higher Risk · Shorter-duration cash flows
Commodity exposure · Illiquidity premium
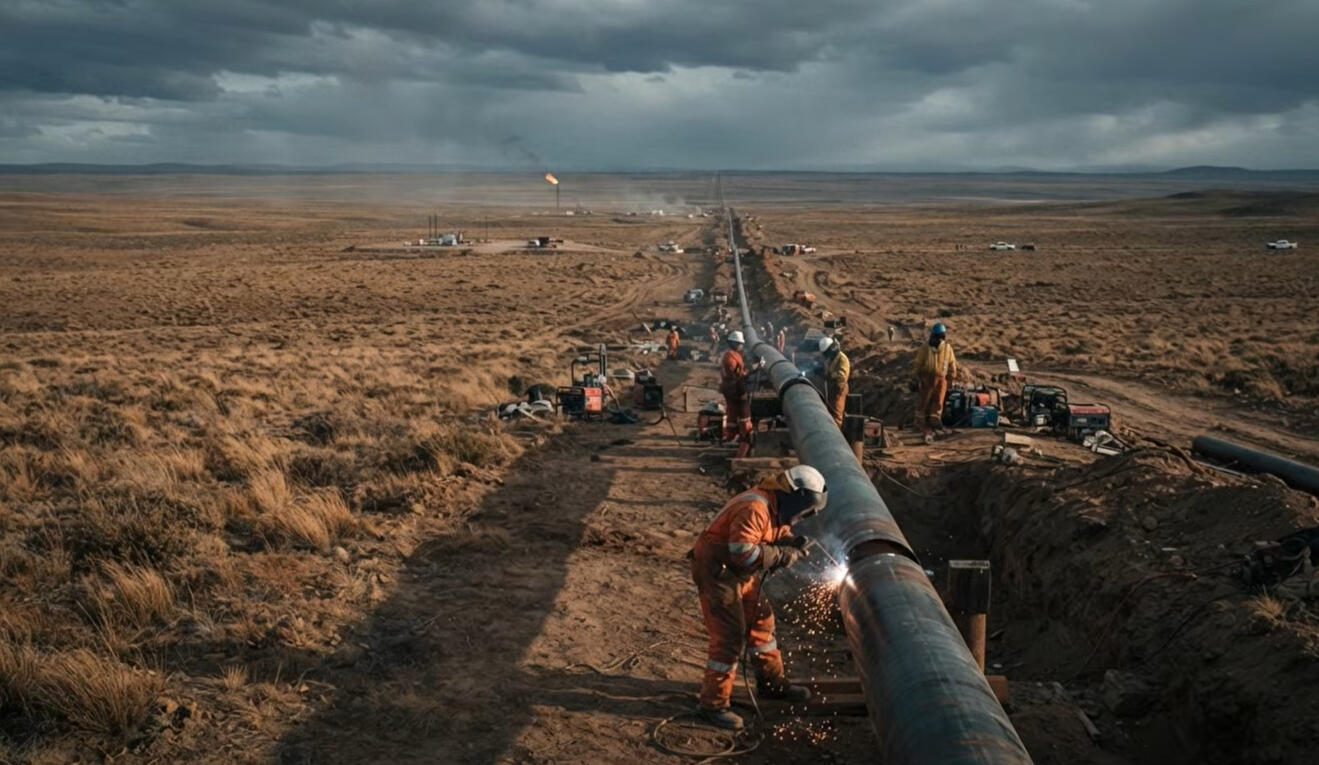
MIDSTREAM / INFRASTRUCTURE
Hydrocarbons Evacuation
Flow-driven assets across pipelines, processing and storage, supporting a growing production base. Economics are substantially less exposed to crude prices and increasingly linked to the expansion of basin volumes and evacuation capacity.
Volume-driven · Lower Brent exposure
Growing basin flows · Longer duration
│ Two investment strategies. One interconnected energy value chain.
The same underlying transformation offers investors differentiated risk / return profiles across upstream production and opportunistic energy infrastructure, accessed through equity, direct lending, asset-backed lending and structured credit.
06. OUR MODEL
How We Work with Investors
Bespoke Ways to Gain Exposure
We focus on Argentina's energy investment case, not on a single financial instrument. Rather than impose a standard portfolio on every client, we structure bespoke opportunities around their specific objectives and risk appetite.
│ We identify the asset and partner first, followed by instrument selection.
UPSTREAM
Equity: Working interests / Farm-in · Partnerships
Credit: Senior secured · Asset-backed
Hybrid: Equity-linked · Convertibles
MIDSTREAM / INFRASTRUCTURE
Equity: Direct ownership · Joint ventures
Credit: Project finance · Asset-backed
Hybrid: Mezzanine · Equity-linked
We work with clients on a non-discretionary mandate basis rather than through a commingled fund structure, allowing opportunities to be tailored to their specific objectives and portfolio requirements.We originate, analyse, value and conduct due diligence on each investment, structure the opportunity, coordinate the legal, technical and transactional work, and support execution through to closing. The investor reviews and approves each investment before committing capital directly to the operating partner.Following investment, we remain actively involved throughout the asset lifecycle, monitoring performance, overseeing the operating partner, reviewing compliance with agreed covenants and investment terms, coordinating local matters and reporting regularly to the investor. We identify issues and opportunities, provide ongoing recommendations and coordinate actions in accordance with the investor’s instructions, through to exit.
Originate → Underwrite → Structure → Approval → Execute → Oversee & Report → Exit
│ The model gives institutional investors direct control over their capital while providing the local presence, sector expertise and investment capabilities required to manage the asset effectively.
07. UPSTREAM: A CLOSER LOOK
Evaluating the Opportunities
A sample analysis of the top 10 oil-producing blocks in Vaca Muerta provides an indication of the asset-level economics available across the basin.
>930
Oil wells analysed
1 MM boe
Avg EUR (Estimated
Ultimate Recovery)
12–26 mths
Capex Payback
Period Range
DPI
Focus on early distribution
of invested capital
7
of the Top 10 fields with
IRR P50 >70% (Pre-Tax)
35%-200%
Gross IRR Range,
P50 (Pre-tax)
9-12 mths
Investment to first
production
P90
NPV10>0 at
$70 Brent
08. THE TEAM
Local Presence. Expertise. Accountability.
Industry relationships, market intelligence and on-the-ground judgement are critical to originating, executing and managing investments in Argentina's energy sector.
MANAGING PARTNER
Max Galland
Swiss-Argentine investment banker / trader turned entrepreneur, with 20+ years in global finance and a longstanding connection to Argentina. Built a career across MUFG, Deutsche Bank, Prudential Financial and ABN AMRO in London, New York and Buenos Aires, trading through multiple market cycles, including major global crises, and specialising in event-driven and special situations strategies across equity and credit markets. Combines international investment expertise with deep knowledge of Argentina's business and financial environment.

Holds a Masters in Finance from London Business School and a Bachelor of Business Administration from Universidad de San Andrés (Argentina).
ARGENTINA-BASED TEAM
80+ yrs of combined experience
Industrial and petroleum engineers with deep expertise across Argentina's upstream and midstream sectors. Our backgrounds span global majors and national leaders, including YPF (Argentina's NOC), Ecopetrol (Colombia's NOC), PDVSA (Venezuela's NOC), Baker Hughes, SLB, Weatherford, BP and Odebrecht.This collective experience brings rigorous technical, operational and commercial know-how developed directly at the heart of the country's most critical energy assets.
09. WHAT NEXT?
Let's talk
We welcome initial conversations with institutional investors seeking strategic exposure to Argentina's evolving energy landscape. This presentation serves as an introduction. We would be pleased to discuss our investment thesis, learn about your investment objectives and requirements, and explore how we might tailor opportunities to your goals.
Email: [email protected]
O: +44.20.7183.0150
For Qualified Investors Only. G.Berthout & Cie. 2026.